

Understanding Debt Cycles and How to Break Free: A Complete Guide
Debt cycles can trap individuals and even entire economies in patterns that are difficult to escape without a clear, deliberate plan. Understanding how these cycles form is the first step toward breaking them.
A debt cycle often begins with borrowing to cover a shortfall, followed by taking on additional debt just to manage the interest and payments on the original amount.
Unexpected expenses, income disruptions, and limited financial cushions all make it easier to fall into this pattern, even for people who manage money carefully most of the time.
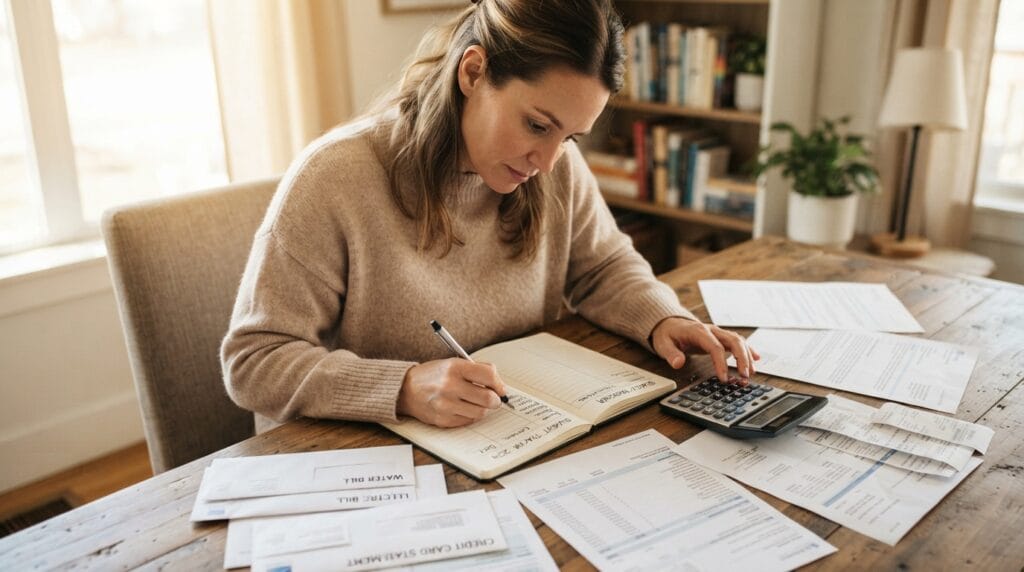
Creating a clear picture of total debt, interest rates, and monthly obligations is an important first step. From there, prioritizing high interest debt while maintaining minimum payments on other obligations tends to reduce the total cost of repayment over time.
Building even a small emergency fund can help prevent new debt from being needed the next time an unexpected expense arises.
Breaking a debt cycle takes time and consistency, but a clear plan combined with realistic budgeting can make meaningful progress possible, even for those who feel overwhelmed at the start.
Understanding debt cycles, break debt cycle, debt repayment plan, financial stability, emergency fund.
Understanding Debt Cycles and How to Break Free
Debt cycles can trap individuals and even entire economies in patterns that are difficult to escape without a clear, deliberate plan. Understanding how these cycles form is the first step toward breaking them.
Table of Contents
How Debt Cycles Form
A debt cycle often begins with borrowing to cover a shortfall, followed by taking on additional debt just to manage the interest and payments on the original amount. Over time, this pattern can grow difficult to sustain, particularly when interest rates are high.
Unexpected expenses, income disruptions, and limited financial cushions all make it easier to fall into this pattern, even for people who manage money carefully most of the time.
Did You Know?
A debt cycle often begins with borrowing to cover a shortfall, followed by taking on additional debt just to manage the interest and payments on the original amount.
Steps to Break the Cycle
Creating a clear picture of total debt, interest rates, and monthly obligations is an important first step. From there, prioritizing high interest debt while maintaining minimum payments on other obligations tends to reduce the total cost of repayment over time.
Building even a small emergency fund can help prevent new debt from being needed the next time an unexpected expense arises.

Key Takeaway
Breaking a debt cycle starts with a clear picture of what you owe. Prioritize high-interest debt, maintain minimum payments on other obligations, and build an emergency fund to prevent future borrowing.
Long Term Financial Stability
Breaking a debt cycle takes time and consistency, but a clear plan combined with realistic budgeting can make meaningful progress possible, even for those who feel overwhelmed at the start.
Related Reading
Explore more analysis on finance and economic wellbeing:
- Warren Buffett's investment principles — Core lessons for beginner investors
- How government welfare programs impact the economy — Understanding economic safety nets